 Paul Arithi
The Monetary Policy Committee (MPC) decided to maintain the Central Bank Rate (CBR) at 8.75 percent, during its meeting held on October 7, 2026.
During its deliberations, the Committee noted that:
• Global growth is projected to moderate in 2026, due to higher energy prices arising from the conflict in the Middle East.
• Global inflation is expected to increase in 2026, mainly on account of higher energy and food prices.
Inflation rates in most major economies have increased in recent months and remained above their respective targets, due to higher energy prices and stickiness of core inflation rates.
Food inflation increased in September 2026, driven by higher prices of edible oils, cereals and sugar.
Central banks in the major economies have remained cautious, with some making modest upward adjustments to their policy rates, while others have kept their policy rates unchanged as they continue to assess the impact of the conflict in the Middle East on their inflation and growth outlooks.
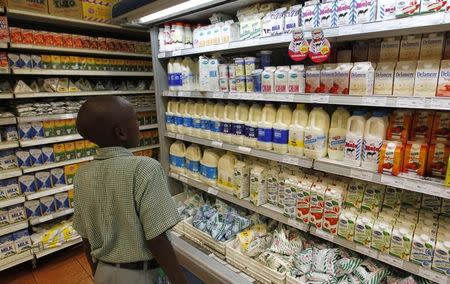
• Kenya’s overall inflation remained within the target range in September 2026 and stood at 6.8 percent compared to 6.6 percent in August.
Core inflation increased to 4.0percent in September from 3.4 percent in August, mainly driven by higher prices of
some processed foods items, particularly milk, wheat products, and edible oils.
Noncore inflation declined to 14.0 percent in September from 14.7 percent in August, reflecting mainly a decline in vegetable prices inflation, and lower energy prices inflation. Government interventions, including subsidies and the temporary reduction of VAT on fuel, continue to mitigate inflationary pressures.
 Overall inflation is expected to remain within the target range in the near term.
This will be supported by appropriate monetary policy actions, government interventions, and a stable exchange rate.
• The projected growth of the economy in 2026 has been revised upwards to 5.0 percent from 4.9 percent, mainly reflecting stronger industry and services sectors.
This is up from 4.6 percent in 2025. Growth in 2027 is projected to remain unchanged at 5.3 percent. This outlook is subject to risks, particularly prolonged geopolitical tensions and elevated trade policy uncertainties, as well as the potential severe impact of the El Niño weather phenomenon.
• The September 2026 Market Perceptions Survey and Agriculture Sector Survey show that most respondents expect some moderate upward pressure on inflation due to high fuel prices, arising from the conflict in the Middle East.
However, respondents expect inflation to remain within the target range in the near term, due to exchange rate
stability, and an expected decline in food prices due to the predicted above average rainfall between October and December 2026.
• The CEOs Survey and Market Perceptions Survey conducted in September 2026 revealed sustained optimism about business activity and economic growth prospects for the next 12 months.
 The optimism was attributed to continued macroeconomic stability,increased Government infrastructure spending, increased digital innovations, and improved private sector credit growth on account of a decline in bank lending rates.
Nevertheless, respondents were concerned about the high energy costs attributed to the conflict in the Middle East, and any disruptions from the expected El Niño rains.
• The current account deficit is estimated at 3.1 percent of GDP in the 12 months to August 2026 compared to 2.1 percent of GDP in a similar period in 2025, due to a higher trade deficit and lower secondary income transfers as a share of GDP.
Goods exports increased by 11.8 percent,mainly driven by horticulture, tea, and machinery and transport equipment. Goods imports increased by 15.8 percent,reflecting higher imports of food, mineral fuels,and intermediate and capital goods.
Services receipts increased by 8.7 percent mainly driven by travel services receipts,while diaspora remittances decreased by 1.3 percent.
The current account deficit is projected at 3.2 percent of GDP in 2026 compared to 2.1 percent of GDP in 2025, mainly reflecting increased imports of mineral fuels on account of higher international oil prices, and
lower remittances.
The current account deficit is expected to be more than fully financed by financial and capital account inflows, resulting in an overall balance of payments surplus of USD 2,426 million in 2026.
 The CBK foreign exchange reserves currently stand at USD 14,702 million (5.9 months of import cover) and continue to
provide adequate cover and a buffer against short-term domestic and external shocks.
• The banking sector remains stable and resilient, with strong liquidity and capital adequacy ratios.The ratio of gross non-performing loans (NPLs) to gross loans stood at 13.9 percent in September 2026, down from 14.8 percent in June 2026, and 17.6 percent in August 2025.
Decreases in NPLs were noted in the financial services, agriculture, trade, and energy and water sectors. Banks have continued to make adequate provisions for the NPLs.
• Growth in commercial banks’ lending to the private sector remained strong at 10.6 percent in September 2026, compared to 10.3 percent in August 2026 and -2.9 percent in January 2025.
Growth in credit to key sectors of the economy, particularly trade,building and construction, agriculture,finance and insurance,and consumer durables remained strong, reflecting improved demand for credit.
Average commercial banks’ lending rates stood at 14.4 percent in September 2026 compared to 14.3 percent in
August, and 17.2 percent in November 2024.
• The Committee noted the ongoing implementation of the FY2026/27 Government Budget, and the planned fiscal consolidation strategy to reduce debt vulnerabilities over the medium term.
Having considered these developments, the Committee concluded that the current monetary policy stance,with the Central Bank Rate unchanged at 8.75 percent,remains appropriate to ensure that inflation expectations remain anchored within the target range, and the exchange rate remains stable.
 The MPC noted that there is need to continue monitoring the evolution of global oil prices and any second-round effects on inflation, as well as other developments in the global and domestic economies,and stands ready to take further action as necessary in line with its mandate.The Committee will meet again in December 2026.
Views: 5