 Aiden k
- Health Insurance:Protecting Your Finances When Illness Disrupts Daily Life
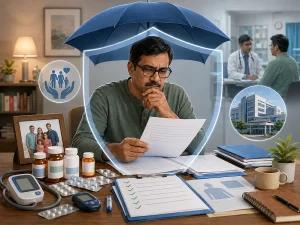
A sudden illness can turn an ordinary month into a financial emergency.A family may have savings set aside for rent, school fees or a business investment, only to find that a hospital admission or a series of consultations requires money immediately.
 Even where treatment is available, the cost of paying for it can force difficult choices about what else the household can afford.
This is why health insurance deserves attention before anyone needs treatment. It provides a way to manage eligible medical expenses under agreed policy conditions,helping individuals and families prepare for costs that may otherwise have to be met from current income or savings.
The challenge is that medical policies are not interchangeable.Two plans described as comprehensive may differ in their benefits, limits, hospital networks, exclusions and out-of-pocket requirements. Choosing cover therefore requires more than comparing premiums.
 Understanding what a medical policy actually pays for
One of the first questions to ask is whether the plan covers inpatient treatment, outpatient care or both. Inpatient benefits generally relate to treatment requiring admission to hospital,while outpatient benefits can cover eligible consultations,tests and other care that does not require admission, depending on the policy.
The distinction matters for households that visit clinics regularly, manage ongoing health needs or have children who need frequent consultations.
A policy with strong inpatient benefits but limited outpatient cover may not suit a family whose main expenses arise from routine visits.
Someone primarily concerned about the financial impact of a major hospital admission may assess the balance differently.
The term “comprehensive” should never replace a careful review.Prospective policyholders need to establish annual limits, sub-limits for specific services, co-payments, deductibles,waiting periods and the treatment of pre-existing conditions.
They should also ask how emergency treatment is handled and whether referrals or prior authorisation are required.
The right cover depends on who needs it
A single professional, a family with young children and a business employing several people will not necessarily need the same arrangement.Their budgets, medical requirements and preferred access to healthcare may differ.
For a family, the decision should account for the number of people insured, the benefits available to each member and whether dependants are covered under the same limits or separate limits.
Parents should confirm how the policy treats newborns, children reaching a specified age and any changes in family circumstances.
 For an individual,affordability matters, but so does the ability to access suitable care.A cheaper policy may be reasonable if its benefits match the person’s needs, while a higher premium may be justified where it offers limits or services that the individual expects to use.
Neither price alone nor a broad marketing description can establish which policy is best.
People should also examine the hospitals and healthcare providers within the insurer’s network.The availability of preferred facilities, the procedure for accessing specialist care and the process for settling bills can affect the practical value of cover.
A policyholder should understand what happens when treatment is sought outside the network or when a hospital requires payment before care is provided.
Medical cover can also support small businesses
For a small employer,health insurance is both a staff welfare consideration and a business expense that needs to be planned carefully.
Employees who lack financial protection may struggle to meet medical costs, while unexpected illness can disrupt their personal finances and their ability to work.
Equity’s SME Health Plan is designed for small and medium-sized businesses, their staff and families. Equity health is another group-oriented option aimed at individuals within a group and their families.
Employers considering these arrangements should request a clear explanation of the benefits, eligibility rules, premium structure and process for adding or removing members.
The business should assess the plan against the size and needs of its workforce.A policy that is affordable at the outset may become difficult to maintain if its renewal costs rise beyond the budget.
Employers should understand how premiums are reviewed and what changes could affect future costs.
Small businesses should also communicate the cover clearly to employees.Staff need to know which facilities they can use, what to do in an emergency, which services require approval and where they may face additional payments. Confusion at the point of treatment can make an otherwise useful benefit harder to access.
Read the exclusions before signing
Policy exclusions and limits often become most important when a claim is made.Waiting periods may apply before certain benefits become available.
Some conditions,procedures or treatments may be excluded or subject to specific requirements.The policy may also set limits for maternity, dental care, optical services, specialist consultations or particular medical procedures.
Anyone with an existing medical condition should disclose it accurately and ask the insurer how it will be treated. Withholding relevant information can lead to disputes or affect a claim.
It is also worth asking how emergency treatment is handled, what documentation is required and how long reimbursement may take where the policy uses a reimbursement model.
Customers should compare the full cost of cover, including premiums and possible out-of-pocket payments. They should consider whether the benefits remain suitable as household circumstances change, rather than renewing automatically without reviewing the policy.
 A financial decision made before illness
Health insurance does not eliminate medical risk, and it cannot guarantee that every treatment or expense will be paid. Its value lies in reducing exposure to eligible costs and making access to covered services more financially manageable.
Equity is one provider offering medical cover to individuals, families, groups and SMEs.Consumers should compare its plans with other available options,paying attention to the details that determine how the policy works in practice.
The best choice is not necessarily the most expensive plan or the one with the longest list of benefits.It is the cover that matches the insured person’s needs,budget and preferred healthcare arrangements.
Medical costs are difficult to plan for when a health problem has already arisen.Reviewing cover while there is time to compare options gives individuals, families and employers a better chance of making a considered decision.
Details of available products can be found on Equity Bank Kenya’s insurance page and its SME and small business insurance page.
 Prospective policyholders should confirm current benefits,exclusions, limits and eligibility directly with the provider before enrolling.
Views: 1