 Aiden k
- Insurance 101 for SMEs:Understanding the Cover Every Business Needs
 However, many operate with limited financial reserves, leaving them vulnerable to unexpected events that can disrupt operations or threaten their survival.
Understanding insurance is therefore an important step towards building a resilient business.
 It helps businesses prepare for specified risks by transferring part of the potential financial burden to an insurer in exchange for a premium.
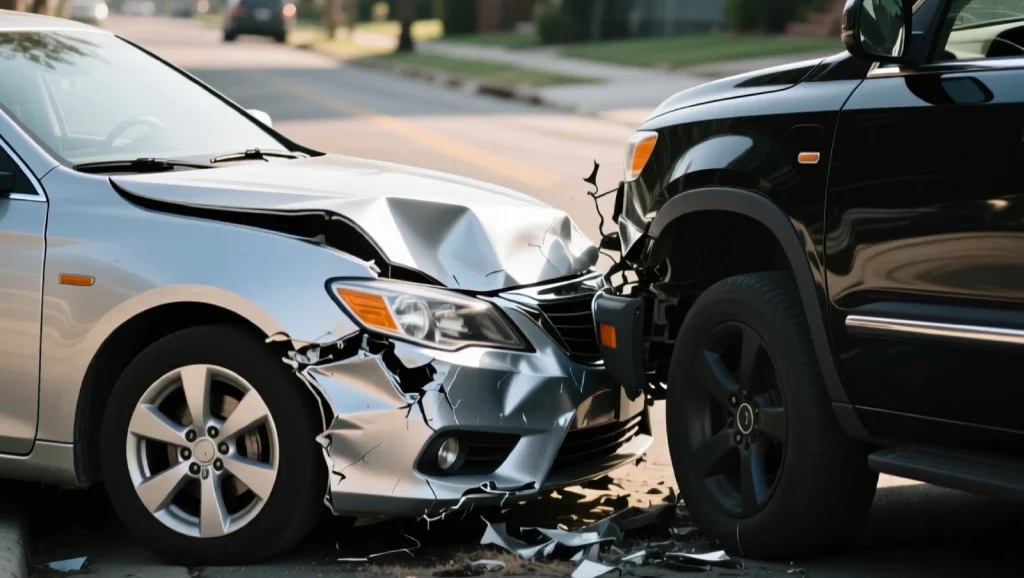
A retailer, for example, may lose stock, furniture and equipment following a fire.Property insurance can compensate the business for covered losses, subject to the policy’s conditions, exclusions and limits. Similarly, a transport operator may require motor insurance, while a manufacturer may need cover for machinery and equipment.
Other forms of general insurance address specific operational risks.Goods-in-transit insurance can protect eligible goods while they are being transported, while public liability insurance may cover specified claims involving injury to customers or damage to third-party property.
 Business interruption insurance can also help compensate for eligible income losses or continuing expenses when an insured event forces operations to stop temporarily.
The right cover depends on the nature of the business, its assets and the risks associated with its activities. Entrepreneurs should assess their exposure before selecting a policy rather than assuming that one insurance product will protect every aspect of their operations.
Life insurance addresses risks associated with the life of the insured individual. Many Kenyan SMEs depend heavily on their founders, whose expertise, financial contribution and customer relationships are essential to daily operations. Losing such a person can affect the business as well as the family that depends on its income.
 Life insurance could provide an investment safety net, providing a business owner with dignified income in retirement or during incapacitation. It can also help meet obligations like paying for children’s school fees.
Life insurance can provide a financial benefit to designated beneficiaries following the insured person’s death, subject to the policy terms.
The proceeds may help dependents meet living expenses, settle financial obligations or support succession arrangements.
Health insurance addresses medical expenses, which can place considerable pressure on business owners and employees.
Depending on the selected plan, cover may include eligible consultations, hospitalisation, prescribed treatment and other approved medical services.
For SMEs, appropriate employee medical arrangements can support staff welfare and help businesses attract and retain skilled workers.
Business owners can enquire about relevant services and any available insurance arrangements, while confirming product availability, coverage and policy conditions directly with the appropriate provider.
Choosing insurance should begin with a straightforward assessment of what the business owns, who depends on it and which losses it could not comfortably absorb.
Entrepreneurs should compare premiums, excesses, exclusions, compensation limits and claims procedures before committing to cover.
Click this link to learn more: https://equitygroupholdings.com/ke/insure/ or visit your nearest Equity Bank branch.
Views: 11